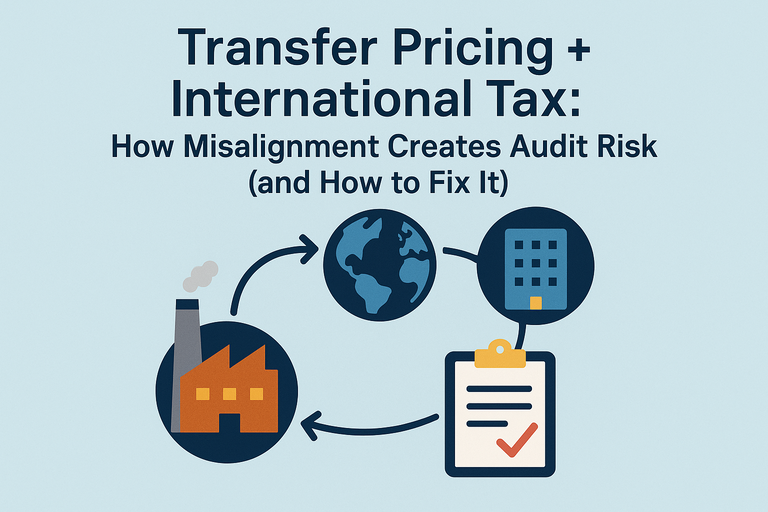
What “misalignment” looks like in real companies
Misalignment isn’t theoretical. It shows up as contradictions between:- Legal structure (who owns what, where)
- Operational reality (who does the work, where)
- Intercompany agreements (what the contracts say)
- Accounting behavior (what you booked)
- Tax filings (what you claimed)
Example of a classic misalignment
- Contract says: foreign subsidiary is the “entrepreneur” taking market risk
- Reality says: US team runs product, pricing, strategy, customer success
- Books say: foreign sub earns high margin, US earns low margin That’s not “tax planning.” That’s an inconsistency begging to be challenged.
Why tax authorities focus on transfer pricing
Because transfer pricing is the easiest way for multinationals to move profit with a journal entry. Tax authorities typically look for:- high-margin entities with little substance
- large service fees with thin support
- royalty payments that don’t match true IP ownership or development
- intercompany financing that strips profits from the tax base
- recurring losses in a local entity that “should” be profitable
The most common transfer pricing risk zones (where audits start)
1) Intercompany services (management fees, support, “shared services”)
Risk triggers:- vague invoices (“management services”)
- no description of deliverables
- no evidence the services were actually performed
- fees that don’t scale logically with activity
- no allocation basis or inconsistent basis year-to-year
2) Royalties and IP licensing
Risk triggers:- unclear IP ownership (who created the IP, who funds development)
- royalty rates that don’t match market reality
- licensing agreements signed after the fact
- “IP company” in a low-tax jurisdiction with no real engineers or control
3) Intercompany financing (loans, cash pooling, guarantees)
Risk triggers:- loans without proper notes and repayment terms
- interest rates that aren’t arm’s length
- debt levels that look like profit stripping
- guarantees and financial support not priced or documented
4) Distribution and sales structures
Risk triggers:- a “limited risk distributor” that actually takes real market risk
- recurring losses in a distributor without a credible explanation
- commissionaire/agent models that don’t match contract and behavior
The ugly truth: “documentation” doesn’t save you if facts are wrong
A transfer pricing report is not a shield if:- intercompany agreements aren’t followed,
- people on the ground act differently than contracts say,
- finance books transactions inconsistently,
- and management can’t explain the business logic.
- emails
- decision-making records
- who approves contracts
- who controls key risks
- where key personnel sit
How to fix misalignment (a practical framework that actually works)
Most companies try to fix transfer pricing with a report. That’s backwards. You fix transfer pricing by aligning business reality → contracts → accounting → tax reporting.Step 1: Map “value creation” honestly
Answer these without spinning:- Who makes the key decisions?
- Who controls budget and strategy?
- Who develops and maintains IP?
- Who manages customer relationships?
- Who bears major risks (market, credit, inventory, warranty, product)?
Step 2: Define roles for each entity (and don’t pretend)
Common roles:- Principal/entrepreneur
- Limited risk distributor
- Contract R&D
- Shared services center
- IP holding/licensing entity
- Routine manufacturer
Step 3: Put intercompany agreements in place before the year runs
At minimum, document:- services scope and pricing
- IP ownership/licensing terms
- financing terms and interest
- distribution/agency terms
- cost allocation methodology
Step 4: Create a transfer pricing policy your finance team can execute
If your finance team can’t operationalize the policy monthly or quarterly, the policy isn’t real. You need:- clear pricing formulas
- clear allocation keys
- clear invoicing cadence
- clear documentation requirements
- clear owners and review procedures
Step 5: Do a year-end sanity check (before filing)
Before returns go out, check:- do margins match the policy?
- do local entities have plausible profit levels?
- do intercompany balances reconcile?
- are invoices and support tied out?
- do disclosures align with the story?
Red flags that tell you you’re exposed right now
If any of these are true, you’re likely misaligned:- Intercompany agreements were signed retroactively
- Fees are booked as “misc” or “other”
- Local entities show losses year after year without a business explanation
- The entity earning the most profit has the fewest people/substance
- Royalties exist but IP development is clearly elsewhere
- Your CFO can’t explain your transfer pricing in one paragraph
- Your tax provider and finance team tell different stories
Where international tax planning fits (so this doesn’t become a recurring fire)
Transfer pricing is downstream of structure. If you structure poorly, transfer pricing becomes a patchwork. Planning helps you:- choose entity models that reflect substance,
- design cash flows that don’t trigger unnecessary withholding,
- align operational footprint with tax objectives,
- avoid strategies that look artificial under scrutiny.