Introduction: Same IC-DISC Rules, Very Different Outcomes
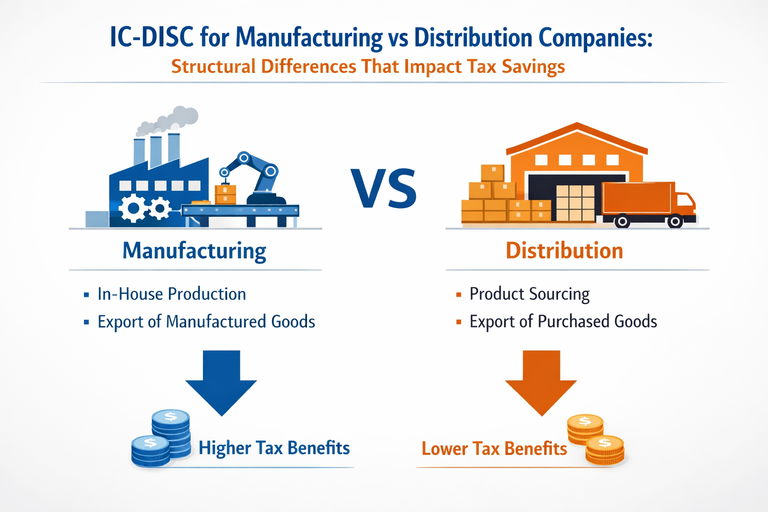
On paper, IC-DISC rules apply uniformly to exporters. In reality, manufacturing and distribution companies experience materially different results under IC-DISC structures. Treating these models as interchangeable is one of the most common—and costly—mistakes exporters make. Structural differences in risk, margin control, and operational substance directly affect both tax savings and audit defensibility.Manufacturing Companies: Where IC-DISC Usually Delivers Maximum Value
Manufacturers typically control:- Product design
- Production processes
- Cost structures
- Pricing strategy
Why Manufacturing Models Work Well
- Higher gross margins support larger commissions
- Clear linkage between U.S. activity and export income
- Easier substantiation of economic substance
Distribution Companies: Where Complexity Increases Risk
Distributors often operate on thinner margins and perform fewer high-value functions.Distribution-Specific Challenges
- Limited pricing authority
- Lower operating margins
- Greater exposure to benchmarking scrutiny
- Food Distributor Case Study
- Are Your Benchmarking Studies Causing Overcompensation to Foreign Distributors?
Functional Differences That Matter to the IRS
The IRS does not classify companies by label. It evaluates what they actually do.Key Functional Distinctions
| Factor | Manufacturer | Distributor |
|---|---|---|
| Product control | High | Low |
| Pricing authority | High | Moderate to Low |
| Risk assumption | Significant | Limited |
| Margin volatility | Moderate | High |
Commission Methodologies: One Size Fails Both
Manufacturers and distributors often default to the same commission calculation methods. This is a mistake.Manufacturer-Friendly Approaches
- Profit-based methods tied to production economics
- Methods reflecting control over IP and processes
Distributor-Specific Adjustments
- Conservative commission caps
- Tight alignment with transfer pricing benchmarks
- Frequent redeterminations
Transfer Pricing Interactions: Where Errors Multiply
Manufacturers and distributors face different transfer pricing pressures.- Manufacturers must defend where value is created
- Distributors must defend why margins are limited
Structural Changes That Break Assumptions
Many companies start as manufacturers and evolve into hybrid models.Events That Require Reassessment
- Outsourcing or contract manufacturing
- Adding foreign distribution entities
- Shifting pricing authority abroad