International Tax Planning for Exporters: Aligning IC-DISC, Transfer Pricing, and Global Expansion

Updated November 3, 2026 International tax planning for U.S. exporters should coordinate export incentives, related-party pricing, and overseas business activities. Start by identifying who sells the products, where business functions occur, and which entities earn the income. Then assess incentives and reporting obligations against those facts. 1. Map Your Export Business Before Choosing a Tax… Continue reading International Tax Planning for Exporters: Aligning IC-DISC, Transfer Pricing, and Global Expansion

Transfer Pricing + International Tax — How Misalignment Creates Audit Risk (and How to Fix It)
If your company operates across borders and you’re treating transfer pricing as “something we’ll deal with later,” you’re not being pragmatic—you’re stacking audit risk. Here’s the core reality: international tax and transfer pricing are the same problem wearing two different hats. International tax sets the rules for where income should be taxed. Transfer pricing is… Continue reading Transfer Pricing + International Tax — How Misalignment Creates Audit Risk (and How to Fix It)
Repatriation Planning — Bringing Cash Back to the US Without Unnecessary Tax Drag

If your company is earning money overseas, you’ll eventually ask the question that separates disciplined operators from reactive ones: “How do we bring cash back to the US efficiently and defensibly?” This is repatriation planning. And despite what many teams assume, repatriation is not just “declare a dividend and wire the money.” It’s a chain… Continue reading Repatriation Planning — Bringing Cash Back to the US Without Unnecessary Tax Drag

Foreign Tax Credits Explained — How to Avoid Double Taxation (and When It Backfires)

If your business earns income abroad, you’ll eventually face the nightmare scenario: the same profit gets taxed twice—once overseas and again in the US. The foreign tax credit (FTC) system exists to reduce double taxation. But here’s the part most companies learn the hard way: Foreign tax credits don’t automatically “fix” double tax. If you… Continue reading Foreign Tax Credits Explained — How to Avoid Double Taxation (and When It Backfires)

Withholding Tax 101 — When US Companies Must File 1042/1042-S (and How Treaties Change It)

If your US company pays non-US persons—contractors, vendors, licensors, lenders, partners—there’s a decent chance you’ve triggered US withholding rules. And here’s the problem: withholding is not a “tax-season” issue. It’s a payment-time issue. If you get it wrong, the IRS can treat you (the payer) as liable for the tax you should have withheld, plus… Continue reading Withholding Tax 101 — When US Companies Must File 1042/1042-S (and How Treaties Change It)

Inbound vs. Outbound International Tax — The Rules, Risks, and Common Mistakes

Most companies get international tax wrong for a simple reason: they don’t even classify their situation correctly. Inbound and outbound international tax are not two flavors of the same thing. They’re different rule sets, different risk profiles, and different compliance triggers. If you mix them up, you’ll choose the wrong structure, miss filings, and discover… Continue reading Inbound vs. Outbound International Tax — The Rules, Risks, and Common Mistakes

Forms 5471, 8858, and 8865: Which Foreign Entity Reporting Form Applies?

Updated November 3, 2026 Form 5471 generally concerns foreign corporations, Form 8858 concerns foreign disregarded entities and foreign branches, and Form 8865 concerns foreign partnerships. However, entity type alone does not establish a filing obligation. U.S. tax classification, ownership, control, reportable transactions, and filing exceptions determine the answer. Start With U.S. Tax Classification A foreign… Continue reading Forms 5471, 8858, and 8865: Which Foreign Entity Reporting Form Applies?

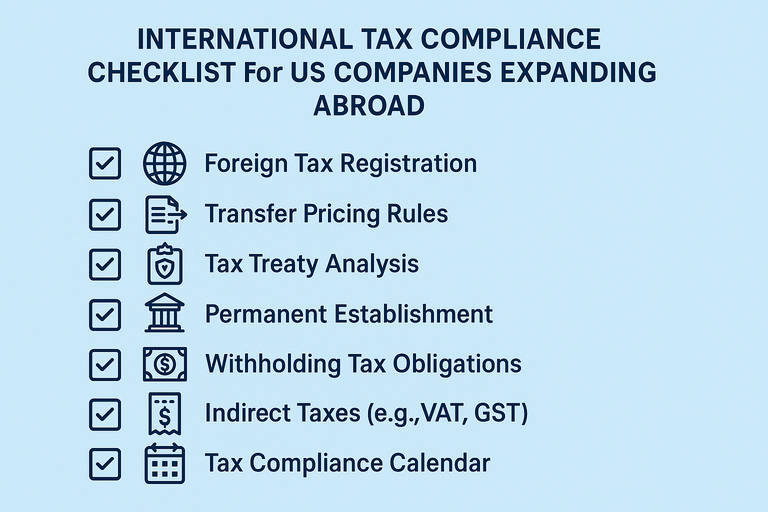
International Tax Compliance Checklist for U.S. Companies Expanding Abroad: The First 90 Days

Updated November 3, 2026 Before expanding internationally, map your activities, confirm entity classifications, identify U.S. and foreign reporting obligations, and assign responsibility for compliance. Review related-party pricing, overseas personnel, bank accounts, and payment arrangements before operations begin. This 90-day checklist is a suggested project schedule, not a legal grace period. Registrations, elections, withholding, or other… Continue reading International Tax Compliance Checklist for U.S. Companies Expanding Abroad: The First 90 Days