Introduction: The Wrong Comparison Costs Real Money
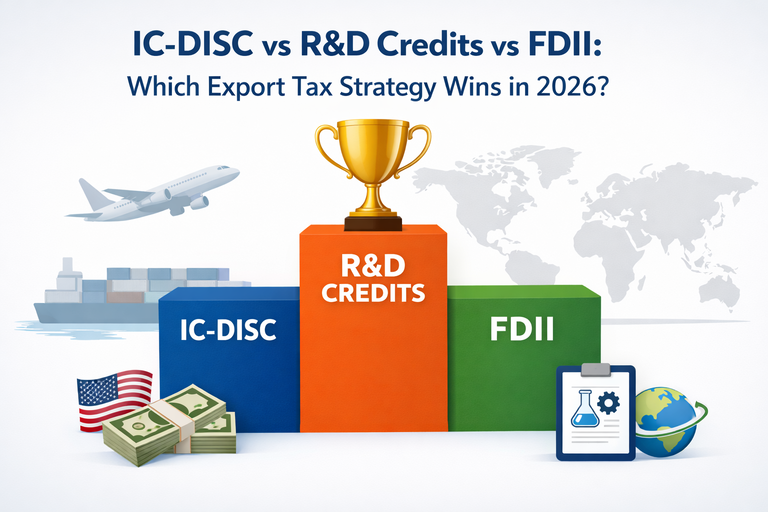
Export-focused U.S. companies are often told they should be using IC-DISC, R&D tax credits, or FDII. What they are rarely told is that these incentives are built for very different economic realities. Choosing the wrong strategy—or stacking them incorrectly—can reduce savings, increase audit risk, or create compliance issues that surface during due diligence. In 2026, with heightened IRS scrutiny and evolving international tax rules, strategy selection matters more than ever. This article breaks down how IC-DISC, R&D credits, and FDII actually work, where each one fails, and how exporters should think about choosing between them.IC-DISC: Profit-Driven, Export-Specific Savings
The IC-DISC regime rewards U.S. exporters by taxing qualifying export profits at a reduced rate through commission-based structures.Where IC-DISC Excels
- Tangible goods exporters
- Companies with consistent export margins
- Businesses with centralized U.S. manufacturing or distribution
Where IC-DISC Breaks Down
- Low-margin exporters
- Service-heavy or IP-driven models
- Companies with fragmented supply chains
R&D Tax Credits: Cost-Based, Not Revenue-Based
R&D credits reduce tax liability based on qualified research expenditures, not export revenue or profit.Where R&D Credits Shine
- Engineering-driven manufacturers
- Software and technology exporters
- Companies investing heavily in product development
R&D Credit Limitations
- No direct link to export activity
- Complex substantiation requirements
- State-level compliance variability
FDII: Attractive on Paper, Fragile in Practice
FDII (Foreign-Derived Intangible Income) was designed to incentivize U.S.-based IP exploitation for foreign markets. In theory, it complements exporters. In practice, it is far more volatile.Where FDII Can Work
- IP-intensive businesses
- High-margin service or licensing models
- Companies with robust documentation
FDII Risk Factors
- Ongoing legislative uncertainty
- Complex income attribution rules
- Increased audit exposure
Head-to-Head Comparison: What Actually Matters
| Factor | IC-DISC | R&D Credits | FDII |
|---|---|---|---|
| Based on | Export profit | R&D spend | Foreign-derived income |
| Stability | High if maintained | Moderate | Low |
| Audit Risk | Moderate | Moderate | High |
| Legislative Risk | Low | Low | High |
| Best For | Exporters of goods | Innovators | IP-driven firms |
Stacking Strategies: Where Companies Go Wrong
Some exporters attempt to stack IC-DISC, R&D credits, and FDII without understanding interaction effects. Common errors include:- Double-counting income
- Misallocating costs across incentives
- Creating inconsistent narratives for IRS exams
What Wins in 2026? The Uncomfortable Answer
There is no universally “best” strategy.- Manufacturers with export margins → IC-DISC often dominates
- Innovation-heavy exporters → R&D credits provide baseline savings
- IP-centric multinationals → FDII may work, but only with discipline
Final Thought: Strategy First, Incentives Second
Tax incentives amplify good structures. They do not fix broken ones. Before choosing between IC-DISC, R&D credits, or FDII, exporters should evaluate:- Revenue mix
- Margin sustainability
- Documentation strength
- Audit tolerance